 TAB Argentina
 TAB Australia
 TAB Austria
 TAB Canada
 TAB Chile
 TAB Czech Republic
 TAB England
 TAB France
 TAB Germany
 TAB India
 TAB Ireland
 TAB Israel
 TAB Lichtenstein
 TAB Mexico
 TAB Moldova
 TAB Netherlands
 TAB New Zealand
 TAB Paraguay
 TAB Portugal
 TAB Romania
 TAB Scotland
 TAB Slovakia
 TAB South Africa
 TAB Spain
 TAB Switzerland
 TAB United States
 TAB Wales
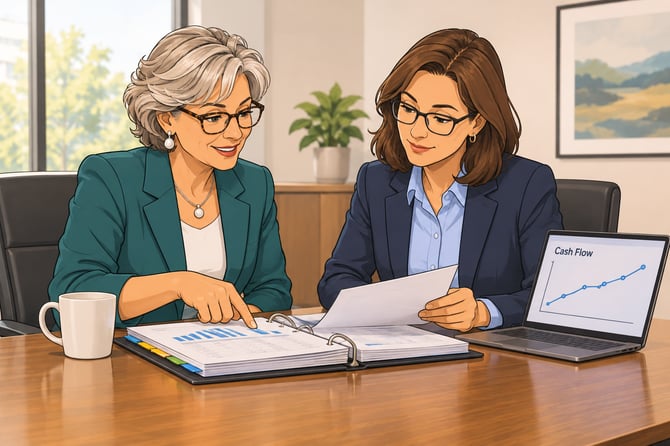
Preparing financials to sell a business means getting your books into a shape a buyer can check line by line. Start one to three years out. Move to accrual statements that close every month, document each add-back with proof, and separate personal spending from business costs. Then track working capital by month and build a diligence file that ties back to your books. Clean records protect your price and speed up the sale.
What Do Buyers Need to See in Your Financials?
A buyer is paying for future earnings, so they need proof of what your company earns, owes, and spends. They will hand your numbers to an accountant, a lender, or both, and every figure has to hold up. When it does, the buyer trusts the rest of your story. When it doesn't, they slow down, ask for more, or lower the offer to cover the risk.
Five areas carry most of that weight: clean accrual statements, add-backs you can prove, separate owner expenses, monthly working capital trends, and a diligence file that ties back to the books. Buyers also weigh things beyond the numbers, like your customers and your team. What strategic buyers look for in a business covers that side in more depth.
Your financials are one part of what a buyer pays for. The free Business Value Driver Scorecard rates the eight traits that buyers, lenders, and appraisers use to set a price, from cash flow to how much the company depends on you. It shows where a buyer would see risk and what to fix first.
Preparing Financials to Sell a Business Starts With Clean Statements
Many small companies keep their books on a cash basis for taxes. Buyers want accrual statements. These match revenue to the month you earned it and costs to the month you took them on, which gives a truer picture of profit. Work through these steps with your accountant:
- Switch to accrual reports. Record revenue when you earn it and expenses when you take them on. Use the same method every month so your trends hold up.
- Close the books each month. Finish your income statement and balance sheet within a few weeks of month end, and save each one.
- Reconcile every account. Match bank, credit card, loan, and payroll balances to your records each month.
- Explain odd balances. Keep short notes on old receivables, owner loans, and anything else a buyer might question.
- Tie your statements to your tax returns. Match annual totals to what you filed and write down the reason for each difference. Fix true errors with your accountant before a buyer finds them.
Twelve clean months is a start. Two or three years of them shows a buyer that clean numbers are simply how you run the company.
How Do You Document Add-Backs a Buyer Will Accept?
Add-backs are expenses a new owner would not have. Buyers add them back to profit to see what the business really earns, so they can raise your earnings figure and your price. They are also the first thing a buyer's accountant will test. Every one needs proof.
- List each proposed add-back, such as a personal expense the company paid or a family member's pay above market rate.
- Pull out one-time costs, like a lawsuit or an office move. Show when each one happened and why it won't come back.
- Keep real costs in. If a new owner must hire a manager to cover your work, or a software fee renews every year, that cost stays.
- Gather proof for each item: invoices, payroll records, and contracts.
- Tie each adjustment to a recorded transaction in your ledger. An add-back with no paper trail is one a buyer will strike.
Be honest with yourself here. A long list of weak add-backs can cost you trust that a short, solid list would have kept.
Separate Owner Expenses From Business Costs
In many owner-run companies, the line between personal and business spending blurs over the years. That is normal, and it is fixable. A buyer will ask about every charge that looks personal, though, and sorting them out late eats time you won't have once a sale is moving.
- Personal charges: flag each one and keep the receipt. A vague label invites questions.
- Shared cards and accounts: move to business-only accounts now, so future months stay clean.
- Owner pay: record your salary, draws, and benefits the same way each month.
- Related-party payments: keep agreements and invoices for money paid to family members or other companies you own.
- Misclassified costs: ask your accountant to correct them so a buyer can follow the cash.
Track Working Capital Month by Month
Working capital is the cash tied up in running the business day to day. It covers what customers owe you, what you owe suppliers, and the stock on your shelves. Buyers often expect a normal level of it to stay with the company at closing, so they want to see what normal looks like for you. A monthly view across busy and slow seasons answers that.
| Area | Compare month by month | What a buyer learns |
|---|---|---|
| Receivables | Amounts owed and days to collect | Whether sales turn into cash |
| Payables | Bills due and days to pay | Whether your payment habits have shifted |
| Inventory | Stock levels and turnover | How much cash sits in unsold goods |
| Cash needs | Lowest cash balance and upcoming bills | How much cash the business needs to run |
| Seasonal patterns | Each month against the same month last year | Which swings are normal for your business |
If a number jumps, write a one-line reason next to it while you still remember why. A note you write today can save a tense phone call during diligence.
Build a Diligence File That Ties Back to the Books
Diligence is when a buyer checks everything you've told them. Picture a buyer asking why sales to your largest customer rose last year. A good file lets you answer in minutes with the contract, the invoices, and the revenue report that ties them together.
Organize the file by year, and make sure every total matches your books. Most buyers will ask for:
- Filed tax returns for the last three years
- Monthly income statements and balance sheets
- A debt list with balances, rates, and payoff terms
- Major customer and supplier contracts
- Payroll records and benefit plan documents
- Your add-back schedule with its proof
Control who can see it. Give access by role, and think through timing for your team. What to tell your employees when selling the business walks through that conversation.
FAQs About Preparing Financials to Sell a Business
- How far ahead should I start preparing my financials to sell?
- Start one to three years before you plan to sell. Buyers want a track record of clean monthly statements, and you need time to switch to accrual reports, separate personal spending, and fix errors. Starting early also gives you time to improve weak numbers before they set your price.
- What counts as an add-back?
- An add-back is an expense a new owner would not have, such as a one-time legal bill, a personal car the company pays for, or above-market pay for a family member. Buyers add it back to profit. Keep an invoice and a short written reason for each one, or expect a buyer to reject it.
- Do I need audited financial statements to sell my business?
- Often you don't. Many smaller sales close with reviewed or well-kept internal statements backed by tax returns. Some buyers and lenders ask for a quality of earnings report, where an outside firm tests your numbers. Ask your accountant which level fits your likely buyers, and expect more scrutiny as deal size grows.
- When should my accountant get involved?
- Bring your accountant in as soon as you start thinking about a sale. They can move your books to accrual, check your add-backs, fix misclassified costs, and spot the gaps a buyer would find. Ask whether they have worked on business sales before, since sale prep differs from yearly tax work.
- Can I sell a business with messy books?
- Yes, but it usually costs you. Buyers price in the risk of numbers they can't check, ask for more protection in the deal, or walk away. Some will want part of the price paid later, based on results. Cleaning up even twelve months of records before you go to market gives you a stronger hand.
Clean financials take months to build, and they pay you back with a smoother sale and fewer surprises at the table. If you are still a few years out, that is good news. Starting your exit planning early gives you room to fix what the numbers show.
TAB helped me in many ways both in growing my business and preparing to sell it. Joining TAB turned out to be one of the best business decisions I ever made, because I knew I needed access to the best ideas and best practices for my business.
Many owners find this work easier with peers who have already sold a company, and that is the heart of how TAB supports business owners. If you want a group of owners to pressure-test your sale prep, find a peer advisory board near you.